

What Is a REIT? Real Estate Investment Trusts Explained
According to Nareit, the REIT industry’s trade association, a REIT is a company that owns, operates, or finances income-producing real estate. The properties range from apartment buildings and warehouses to shopping centers, medical facilities, data centers, and cell towers. To qualify as a REIT, a company must pay at least 90% of its taxable income to shareholders, and most pay out all of it. That rule is why REITs are known as dividend investments.
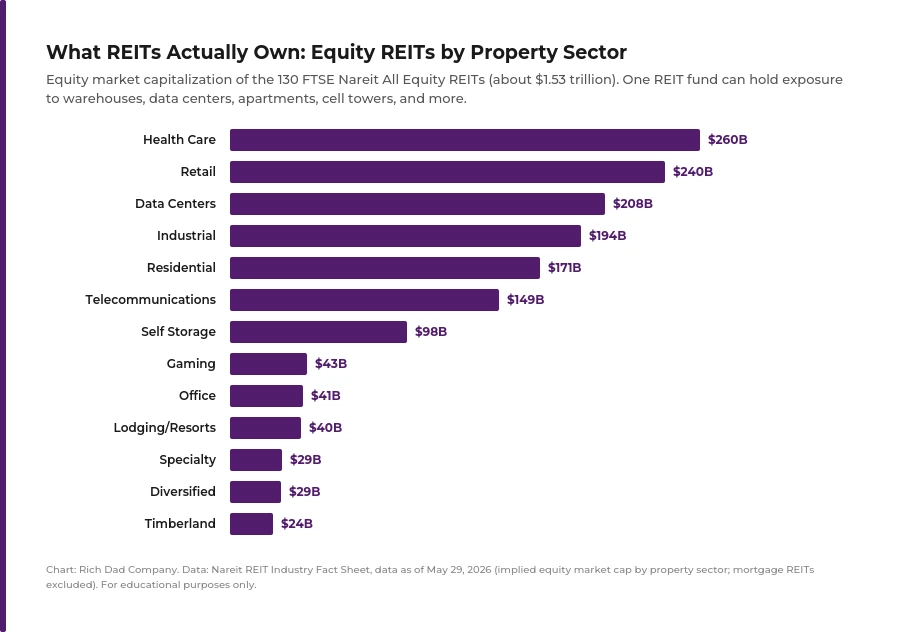
Nareit estimates that about 170 million Americans live in households that own REITs, mostly through 401(k)s, IRAs, and funds. That reach makes REITs one of the most common ways ordinary investors touch real estate. Most REITs hold a mix of property types, and the largest listed sectors by market value are health care, retail, data centers, and industrial properties.
Types of REITs: Equity, Mortgage, and Hybrid
REITs fall into three main categories, each with a different source of income and a different risk profile:
- Equity REITs own and operate properties and earn most of their income from rent. They are the most common type and are known for steady income and the potential for long-term appreciation.
- Mortgage REITs (mREITs) lend money to property owners or buy mortgages and mortgage-backed securities, earning interest. They tend to be more sensitive to interest rate changes and can carry more risk.
- Hybrid REITs combine both approaches, holding properties and mortgages in the same portfolio.
REITs also differ in how they are sold. Publicly traded REITs trade on stock exchanges like any other share. Public non-traded REITs do not, and FINRA, the brokerage industry regulator, cautions that they tend to be less liquid and that fixed-price versions may be appraised only about once a year. Private REITs are generally limited to certain investors.
How to Invest in REITs: REIT Stocks, ETFs, and Funds
Most investors buy REITs in one of two ways:
- REIT stocks: Individual REITs can be bought through a brokerage account like any other stock. This route allows research into a specific company, its properties, its debt, and its management.
- REIT ETFs and mutual funds: These pool investor money to buy shares in many REITs at once, which provides instant diversification and professional management.
There is a catch with funds. Buying a fund makes it much harder, if not impossible, to conduct due diligence on the property managers and companies controlling the underlying investments. Rich Dad education treats that due diligence as part of the investor’s job, which is why it pairs REIT investing with stocks and paper assets education. Before buying any REIT, investors typically study its funds from operations (FFO), occupancy, debt levels, and the track record of its management team.
A simple process keeps the steps in order:
- Learn the basics first. Understand REIT types, property sectors, and how dividends are taxed before committing money.
- Choose the vehicle. Individual REIT stocks allow company-level research. ETFs and mutual funds trade that depth for diversification.
- Research the REIT. Review funds from operations, occupancy, debt, dividend coverage, and management’s track record.
- Choose the account. Because most REIT dividends are ordinary income, many investors consider holding REITs in tax-advantaged accounts. A tax professional can advise.
- Start small and monitor. Size positions so one REIT cannot sink the portfolio, and review debt, interest rates, and sector news regularly.
REIT Pros and Cons at a Glance
Here is the short version before the detail. Each point is covered in the sections that follow.
| Pros | Cons |
|---|---|
| Passive dividend income from real estate | Returns have trailed the S&P 500 over 20 years |
| Liquidity for publicly traded shares | Dividends are mostly taxed as ordinary income |
| Diversification across properties and markets | No personal leverage or control over the property |
| Professional management | Sensitive to interest rates and market swings |
| Low starting capital compared with buying property | Non-traded REITs can be hard to sell |
Are REITs a Good Investment? The Case for REITs
REITs earn their place in a portfolio for a handful of practical reasons.
Passive Income From Real Estate
Because REITs must distribute most of their taxable income, they tend to pay higher dividends than the broader market. As of May 29, 2026, equity REITs averaged a dividend yield of 3.69%, compared with 1.02% for the S&P 500, according to Nareit. For investors who want passive income without tenants, that is the core appeal.
Liquidity
Traditional real estate can take months to sell. Publicly traded REIT shares can be sold on any trading day, which makes a REIT position far more flexible than a building.
Diversification and Professional Management
One REIT holding can spread exposure across many properties, tenants, and markets, and a professional team handles acquisitions, financing, and operations. Nareit also cites a CEM Benchmarking study showing listed REITs averaged 9.7% a year from 1998 to 2022, compared with 7.7% for private real estate. That result comes from an industry source, so it is best read as one data point rather than a verdict.
The Case Against REITs: Risks and Drawbacks
Rich Dad education treats risk as a reason to learn more, not a reason to stay away. The risks of REIT investing fall into five areas.
REIT Returns Have Trailed the Stock Market
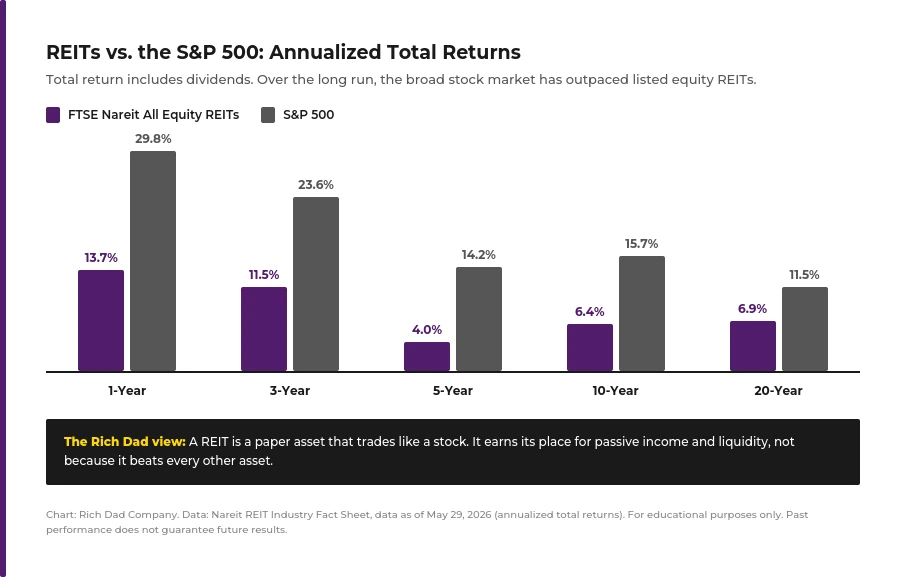
Income is not the same as total return. In every period shown below, listed equity REITs trailed the S&P 500, including a 6.9% annualized return over 20 years versus 11.5% for the index. REIT investors are paid in dividends, but they have not been paid more than the market for taking on real estate risk.
Market and Interest Rate Risk
REIT shares move with the stock market and with interest rates. Higher rates raise borrowing costs for property owners and can pressure property values, and mortgage REITs are especially sensitive. Results also vary widely by sector. Nareit’s 2026 mid-year update reported a 14.9% total return for equity REITs through mid-2026 and noted that only five of 13 sectors were positive in 2025, with health care up 28.5% and data centers down 14.2%. Nareit argues that fixed-rate debt and longer maturities have helped REITs weather higher rates, but that depends on the individual REIT.
Management and Leverage Risk
A REIT is only as strong as its management team. Overpaying for properties or running assets poorly can hurt returns. Many REITs also borrow to buy property, which can boost returns in good markets and magnify losses in bad ones. Investors should check a REIT’s debt levels, loan maturities, and whether its borrowing is fixed-rate or floating-rate.
The REIT Tax Drawback
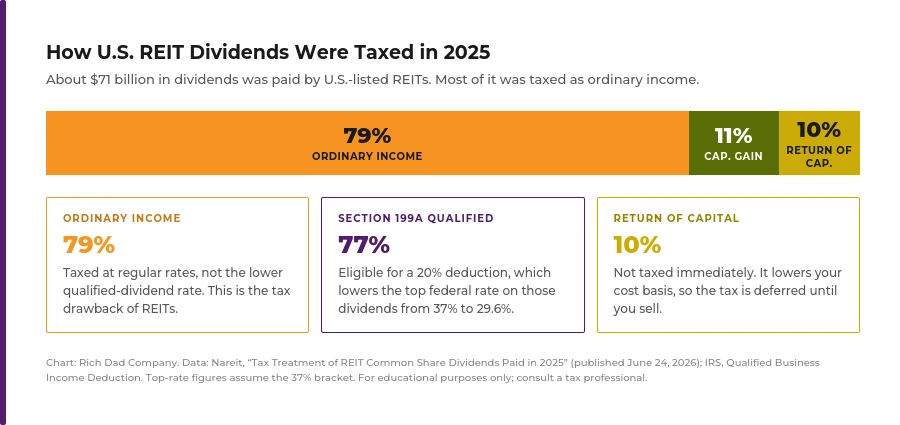
Rich Dad investors value real estate in large part for its tax treatment. REITs deliver less of it. Nareit reported that about 79% of the roughly $71 billion in dividends paid by U.S.-listed REITs in 2025 was ordinary income, 11% was long-term capital gain, and 10% was return of capital. REIT dividends generally do not receive the lower qualified-dividend rate.
There is a partial offset. About 77% of those dividends qualified for the 20% Section 199A deduction, which Nareit says lowers the top federal rate on qualifying dividends from 37% to 29.6%. REIT shareholders also do not claim the property’s depreciation themselves. Depreciation works at the REIT level and reaches investors only indirectly, such as through the return-of-capital portion of a dividend. A direct owner, by contrast, can often use depreciation and expense deductions to reduce taxable rental income. A tax professional can explain how these rules apply to a specific situation, and the personal taxes hub covers the basics.
No Personal Leverage or Control
The other advantage of direct real estate is leverage. Rich Dad education teaches investors to use good debt, often called other people’s money, to control a larger asset than their own cash could buy. Inside a REIT, the borrowing is done by the company. A shareholder cannot choose the property, negotiate the loan, set the rents, or decide when to sell.
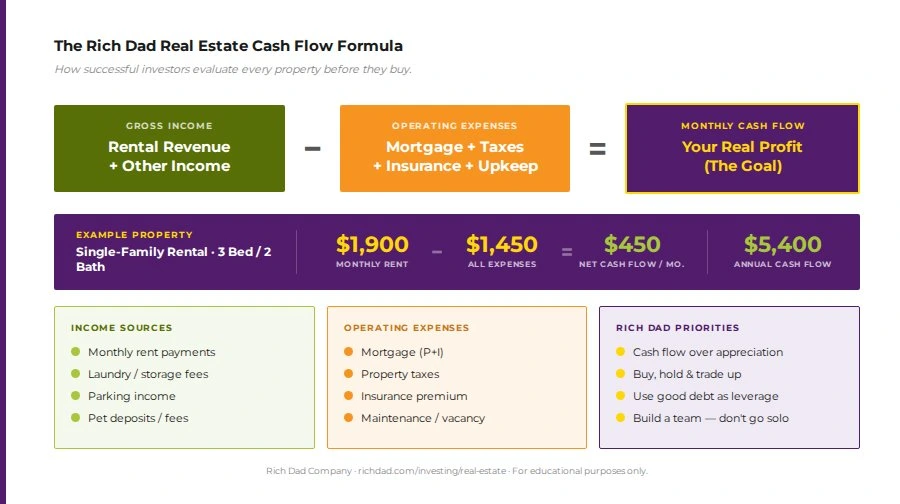
That control is what makes the cash flow formula work for a direct owner: rental income minus mortgage, taxes, insurance, and upkeep equals monthly cash flow. The investor sets every variable in that equation, and the real estate cash flow evaluator helps test a deal before buying.
REITs vs. Owning Rental Property
Neither choice is automatically better. The table below compares how each fits the principles Rich Dad investors use to evaluate an asset.
| Factor | REITs | Direct Rental Property |
|---|---|---|
| Effort | Minimal. Management is handled by the REIT. | Hands-on, or paid to a property manager. |
| Liquidity | High for publicly traded shares. | Low. Sales can take months. |
| Leverage | Borrowing happens inside the REIT. The investor has no personal loan terms. | The investor chooses and negotiates the financing. |
| Taxes | Dividends mostly taxed as ordinary income; 199A deduction may apply. | Depreciation and expense deductions may reduce taxable rental income. |
| Control | None over property, tenants, or timing of sales. | Full control over property, rents, and exit. |
| Starting capital | The price of a share. | Down payment, closing costs, and reserves. |
Investors who want to see how direct ownership works can start with the real estate investment strategies guide and the rental property passive income guide.
Can You Get Rich Investing in REITs?
Probably not from REITs alone. The Nareit data shows REITs working best as an income and diversification tool. Equity REITs yielded 3.69% versus 1.02% for the S&P 500, but returned 6.9% annualized over 20 years versus 11.5% for the index. As a hypothetical, $10,000 compounding at 6.86% for 20 years grows to about $37,700, while the same amount at 11.45% grows to about $87,400. Past performance does not guarantee future results.
Rich Dad education points to the factors that tend to build larger wealth: leverage, tax advantages, control, and the knowledge to use them. A REIT share offers less of each. That is why Rich Dad investors treat REITs as one asset among several rather than the whole plan.
REIT Investing Strategies for Income and Growth
Before adding options, most REIT investors start with a handful of core strategies:
- Diversify across sectors. 2025 results ranged from health care up 28.5% to data centers down 14.2%, so holding one property type concentrates risk.
- Pair a core fund with selective picks. A broad REIT fund provides diversification, and individual REITs can be added where the investor has done the due diligence.
- Reinvest dividends. Using dividends to buy more shares compounds the position over time, though taxes still apply to the dividends.
- Match the REIT to the goal. Income-focused and growth-focused REITs behave differently, and an unusually high yield can signal that the market doubts the dividend is sustainable.
Advanced REIT Investing Strategies: Using Options to Supercharge REIT Income
Because REITs trade like stocks, investors can apply options strategies to them. Options give the buyer the right, but not the obligation, to buy or sell a stock at a set price, called the strike price, before an expiration date. A call option is the right to buy; a put option is the right to sell. Options carry real risk and require education, which is why Rich Dad teaches them as part of its options trading for cash flow approach.
Covered Calls on REITs
An investor who owns REIT shares sells call options on them and collects a premium. If the share price rises above the strike price, the shares may be called away, which caps the upside. The strategy suits investors who expect modest gains and want extra income.
Protective Puts
An investor who owns a REIT and worries about a decline buys put options as insurance. If the price falls below the strike price, the put offsets the loss. The premium reduces overall return, so the protection has a cost.
Cash-Secured Puts
An investor sells a put option on a REIT they would be willing to own and sets aside the cash to buy it. If the price stays above the strike price, the option expires and the investor keeps the premium. If it falls below, the investor buys the shares at the strike price, which may be above the market price.
Vertical Spreads
A vertical spread buys and sells options on the same REIT with the same expiration date but different strike prices. A bull call spread, for example, limits both the cost and the potential profit when an investor expects a moderate rise.
Used well, options let a REIT investor double-dip: dividends from the REIT, plus premium income from options. Used poorly, they can create losses. A written risk management plan and the investing for cash flow with stocks guide are good places to start, and starting small is part of the plan.
How Rich Dad Investors Evaluate a REIT: Five Questions
Rich Dad education suggests asking the same five questions before any investment, REITs included:
- Is this inside my circle of knowledge? Can the investor explain the REIT’s properties, tenants, debt, and how it makes money?
- Does it generate cash flow? Robert Kiyosaki’s Rich Dad philosophy defines an asset as something that puts money in your pocket. REIT dividends can qualify, but the investor should confirm they are covered by the REIT’s cash flow.
- What are the tax advantages? Know how the dividends will be taxed before investing, not after.
- What is the real risk, and can I control it? Identify interest rate, management, leverage, and liquidity risks, then decide whether the investor’s knowledge can manage them.
- Do I have the right team in place? A CPA, attorney, and broker can catch mistakes an investor does not yet know to look for. Their role is to support the investor’s own education, not replace it.
If an investor cannot answer all five questions confidently, that is not a no. It is an education assignment, and closing that gap is the first step.
Conclusion: Are REITs Worth Adding to Your Portfolio?
REITs are a reasonable way to add real estate income and liquidity to a portfolio without owning property. They also give up the leverage, control, and tax advantages that make direct real estate a Rich Dad favorite, and in the periods measured above they have trailed the stock market. For many investors, REITs work best as one piece of a broader plan built on financial education, rather than a substitute for it. The next step is to learn how REITs, rental properties, and real estate investing strategies compare, then decide where each fits.
This article is for educational purposes only and is not financial, tax, or legal advice.
FAQs
A REIT, or real estate investment trust, is a company that owns, operates, or finances income-producing real estate. Investors buy shares, and the REIT must distribute at least 90% of its taxable income as dividends. That is how shareholders collect real estate income without buying or managing a property.
REITs can produce steady dividend income, but the data points to income and diversification rather than fast wealth. Listed equity REITs returned 6.9% annualized over the 20 years ended May 29, 2026, versus 11.5% for the S&P 500. Rich Dad investors typically look for the leverage and control of owning assets directly, which REIT shares do not offer.
Equity REITs earn rent from tenants. Mortgage REITs earn interest on mortgages and mortgage-backed securities. Shareholders benefit through dividends and any change in the share price.
Mostly. About 79% of U.S. REIT dividends paid in 2025 were ordinary income, 11% were long-term capital gain, and 10% were return of capital. Many REIT dividends also qualify for the 20% Section 199A deduction. A tax professional can explain how this applies to an individual’s situation.
Yes. REIT shares fluctuate with the stock market, interest rates, property values, and management decisions. In 2025, only five of 13 equity REIT sectors were positive, and data centers fell 14.2%. Non-traded REITs add liquidity risk because shares may be hard to sell.
No one can reliably time a market low. Rich Dad education encourages investors to learn how interest rates and economic cycles affect REIT prices, check each REIT’s debt and management, and have a plan before buying, rather than reacting to a price drop alone. This is education, not personal advice.