
What Is Bad Debt? The Rich Dad Definition
Rich Dad defines bad debt as borrowing that finances a liability: something that takes money out of your pocket each month and never pays you back. A loan earns the label “good debt” only when the asset behind it produces enough income to cover the payment and leave cash over. Everything else drains your cash flow, whatever the interest rate happens to be.
The asset and liability test
The test starts with Rich Dad’s definitions of assets and liabilities. An asset puts money in your pocket each month. A liability takes money out. Context decides which is which. Take a truck. As a personal vehicle, it costs you a loan payment, insurance, taxes, maintenance, and repairs, so it is a liability. As part of a construction fleet where the income more than covers those costs, the same truck is an asset.
The debt follows the same logic. A loan for the personal truck is bad debt because it finances a liability. A loan for the work truck can be good debt because it buys something that pays you each month.
Bad debt in accounting vs. personal finance
If your search for “what is bad debt” turned up accounting pages, that is a different meaning. In accounting and tax, bad debt is money owed to a business or lender that can no longer be collected, which can sometimes be written off. This guide covers the personal finance version: money you owe, and whether it builds your wealth or drains it.
Bad Debt Examples: What Counts and What Doesn’t
Bad debt shows up in a few familiar forms. Each one borrows against something that cannot repay the loan.
- Credit card balances carried month to month
Most people use cards to finance things that get consumed or lose value, such as clothes, electronics, dining, and travel, then make only minimum payments. - Loans for depreciating purchases
Car loans, furniture financing, and borrowing for vacations tie a monthly payment to something worth less every year. - High-cost loans
Payday loans, title loans, and many unsecured personal loans are priced for borrowers with the fewest options. - Emergency borrowing
Rich dad called debt taken on only in emergencies the worst debt of all. It usually signals a household living paycheck to paycheck, with few assets and many liabilities.
The gray zone: mortgages, student loans, and buy now, pay later
Some debts depend on how you use them. A mortgage on the home you live in finances a liability, because your home takes money out of your pocket through the payment, taxes, insurance, and upkeep. That does not make homeownership a mistake. It means the loan belongs on the liability side of your ledger, not in your investment plan.
A student loan behaves like good debt only if the income it creates comfortably covers the payment. A large loan with no clear path to higher earnings behaves like bad debt no matter how worthy the purpose. Buy now, pay later plans face the same test: if you borrowed for something that is already consumed, it is bad debt in smaller pieces.
Why Bad Debt Is So Risky and Expensive
Bad debt does damage in three ways. It costs more than almost any other kind of borrowing, it is hardest to carry when income stops, and it gets no help from the tax code.
Interest works against you
Credit cards sit at the top of the cost ladder. The Federal Reserve’s latest preliminary figures show personal loans near 11.9% and new car loans near 7.5%, while the 30-year mortgage averaged 7.40% in the week of October 8, 2026. A card balance costs roughly three times as much as a mortgage, and it buys something that cannot pay the interest back.
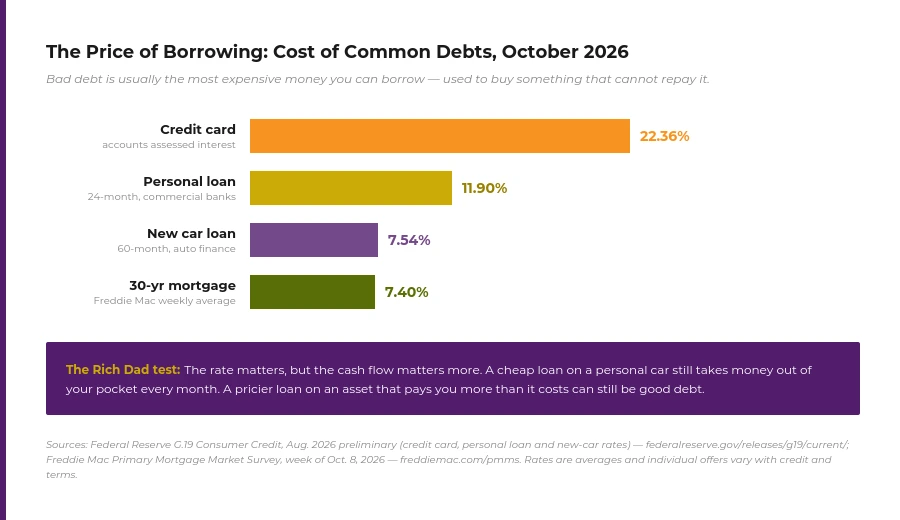
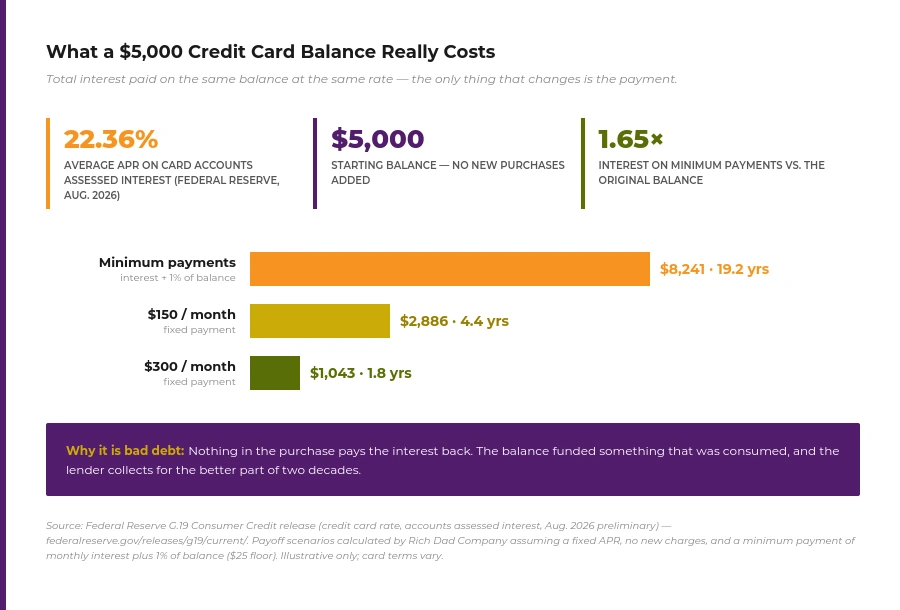
The cost compounds with time. Imagine a $5,000 balance at 22.36% with no new purchases added. If you pay only the monthly interest plus 1% of the balance, it takes about 19 years to clear and costs roughly $8,241 in interest, about 1.65 times the original balance. Raise the payment to $300 a month and the same balance is gone in under two years for about $1,043 in interest. The balance did not change. The payment decided what it cost.
Bad debt is hardest to carry when income stops
Rich dad said it plainly: “Follow the money.” In his view, people who borrow out of necessity are the ones with the least cash flow to repay, which is why the financial industry is happy to see people take on only bad debt. Without assets paying you each month, every payment depends on a paycheck. Lose the paycheck and the debt keeps running.
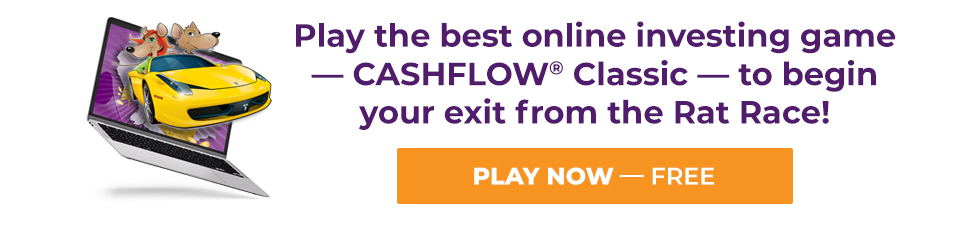
The national numbers show the same pattern. Debt secured by a property, like a mortgage, falls behind least often. Debt with no asset behind it, like card balances, falls behind far more often.
Bad debt gets no tax help
The tax code treats borrowing for consumption differently from borrowing to invest. According to the IRS, personal interest generally can’t be deducted, which covers credit card interest and, in most cases, car loan interest, with a narrow, income-limited exception for certain new U.S.-assembled vehicles in tax years 2025 through 2028. Home mortgage interest and investment interest can be deducted within limits, and student loan interest can be deducted up to $2,500 before income phase-outs. Bad debt gets no help. Confirm how the rules apply to your situation before you rely on any deduction.
Poor Dad vs. Rich Dad: Two Ways to Use Debt
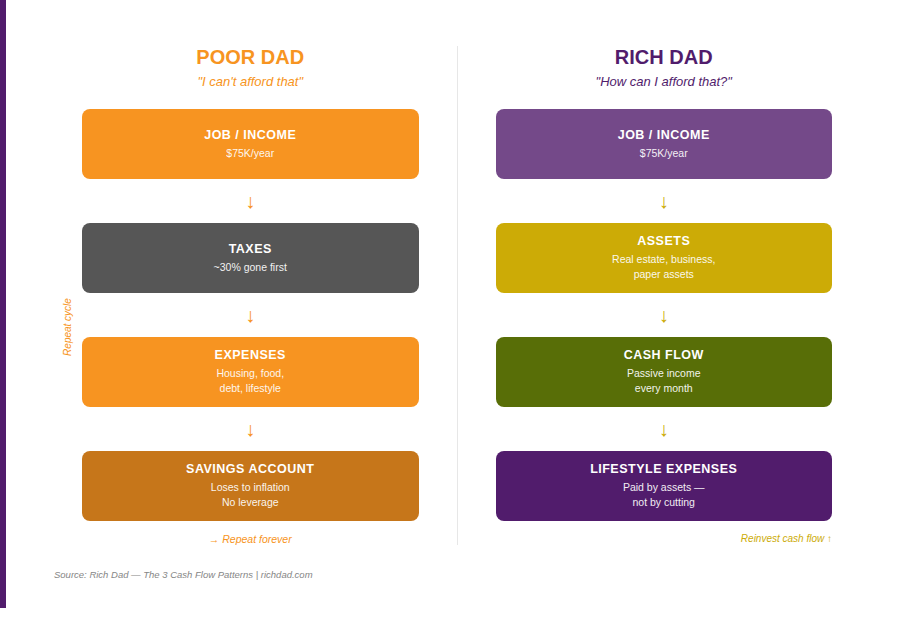
Poor dad saved money, then spent it. He bought things with cash whenever he could, and used debt only when an emergency forced him to. Rich dad agreed on one point: liabilities like cars and televisions are best paid for in cash rather than financed. Where they split was what debt could do. Rich dad borrowed money that made money for him, then used the income to pay for the things poor dad saved up for.
The two paths look the same on payday and very different five years later. The pattern is one reason Rich Dad questions the advice to live below your means: cutting back protects the paycheck, but it does not build the assets that replace it.
How Good Debt Works Instead
A simple definition of good debt is debt that puts money into your pocket rather than taking money out. A financially intelligent investor will not take on a loan unless the asset’s income pays the debt payment and expenses and leaves a return. Rich Dad’s guide to good debt versus bad debt goes deeper on the cash flow test, and this example shows why the test comes first.
Say you have $100,000 and a rental market where a $100,000 property nets $800 a month after taxes, insurance, maintenance, and vacancy. Buy one property with cash and you collect $9,600 a year, a 9.6% return. Or put 20% down on five properties with 30-year loans at 7.40%. Each $80,000 loan costs about $554 a month, leaving about $246 in cash flow per property, or roughly $1,230 a month across all five. That is about $14,760 a year, a 14.8% return on the same $100,000, because the properties earn 9.6% of their price while the loan payments cost 8.3% of the amount borrowed. This is how real estate investors use debt to build wealth.
The same math shows the risk. If net rent slipped from $800 to $600, cash flow per property would fall to about $46 a month, or $230 across all five. The numbers here are hypothetical and illustrate the principle, not a forecast. Good debt is a skill, and the cash flow test has to pass before you sign.
The Great Recession showed the difference at scale. While many people were frightened of debt and others were sinking under sub-prime mortgages on homes they were told were assets, Rich Dad Real Estate Advisor Ken McElroy and Robert Kiyosaki used low-cost commercial loans to buy multifamily properties at depressed prices. According to Rich Dad, many of those properties later sold for many times what they paid.
How to Turn Bad Debt Into Good Debt
Getting from bad debt to good debt is a sequence, not a single move.
- Stop adding new bad debt
No new balances on things that will be consumed or lose value. - Write down every debt
List the balance, the rate, and what each loan financed. A personal financial statement shows which debts sit behind liabilities. - Pay down the highest-rate balances first
Keep paying the minimum on the rest, then roll each freed-up payment into the next balance. Rich Dad’s formula for paying off credit card debt walks through the math. - Redirect the freed-up payments into assets
Every payment you retire becomes cash flow you can aim at something that pays you back, once you have the financial education to evaluate it. - Borrow again only for assets that pass the cash flow test
The income has to cover the payment with a margin to spare.
For the full plan, see Rich Dad’s step-by-step guide to getting out of bad debt or the book Rich Dad’s Guide to Becoming Rich Without Cutting Up Your Credit Cards.
The Bottom Line on Bad Debt
Debt is not the villain Robert Kiyosaki’s poor dad believed it to be, and it is not a shortcut either. Bad debt buys liabilities and takes money out of your pocket every month. Good debt buys assets and puts money in. The financial education to tell the difference, and to run the cash flow test on every loan, is what separates people who work for money from people whose money works for them.
FAQs
A credit card balance carried month to month for clothes, electronics, or travel is the classic example. The purchase loses value or is consumed, it produces no income, and the interest keeps costing you every month.
By Rich Dad’s definition, a personal residence is a liability because it takes money out of your pocket each month. A mortgage on it finances that liability. That does not mean you should not own a home. It means you should not count it as an investment.
It depends on the income the education creates. A loan that raises your earnings enough to cover the payment comfortably can behave like good debt. A large loan with no clear income payoff behaves like bad debt.
In accounting, bad debt is money owed to a business that it cannot collect, which it can write off. That is different from the personal finance meaning, which is borrowing that finances liabilities and drains your cash flow.
Robert Kiyosaki teaches using debt to acquire cash-flowing assets such as rental real estate, structured so the income covers the payment and leaves cash over. His own story starts with a Hawaii condo financed on a credit card and paid for by the rent.
Stop adding new balances, list every debt with its rate, and pay down the highest-rate balances first while keeping minimums on the rest. Then redirect the freed-up payments toward assets that pay you back.